Engineered
Creativity
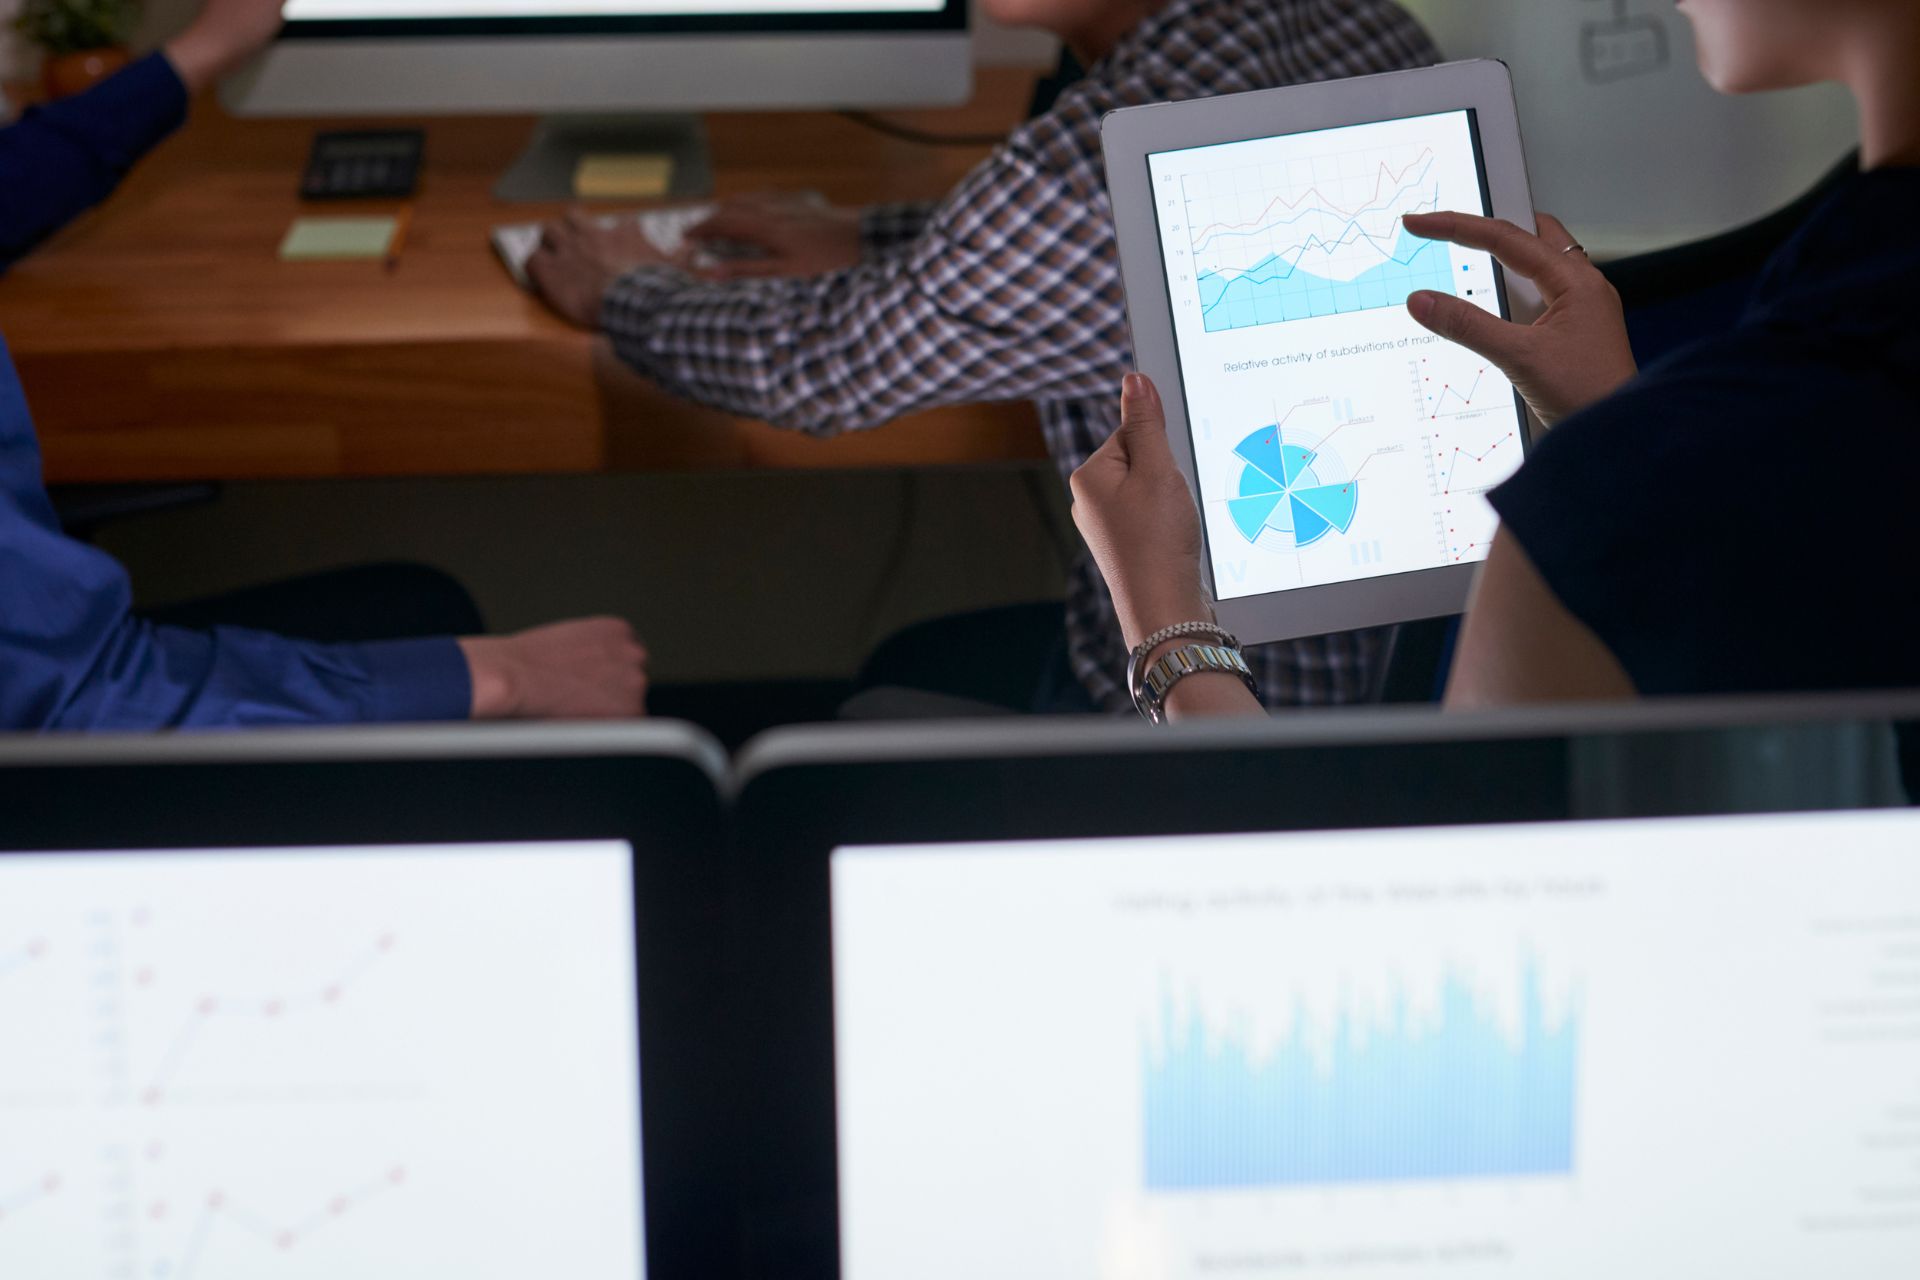
Factor models transform raw returns into interpretable exposures: market beta, size, value, profitability, investment, momentum or custom risk premia depending on the framework.
01 / From performance to explanation
A return series alone tells you what happened. A factor regression starts asking why: was performance driven by market exposure, style exposure, sector structure, leverage, or something that looks like residual alpha?
02 / Why data quality matters
Factor outputs depend on the source, frequency, region, construction methodology and rebalance timing. Even a clean regression becomes misleading if the factor library and portfolio universe do not match.
03 / Portfolio use
Factor dashboards are useful when they show exposure, confidence, rolling stability and drawdown contribution. The point is not to decorate a report: it is to catch hidden bets before they become expensive.
The objective is not to make risk look mathematically impressive. It is to make uncertainty visible enough to be acted on.
Reference note: Kenneth French Data Library.